Coherent (COHR) is a vertically integrated photonics company supplying optical transceivers, lasers, components, materials, and manufacturing systems. Its Datacenter and Communications segment is the main growth engine, serving AI data centers, telecom networks, and high-speed connectivity markets, while Industrial supports semiconductor equipment, precision manufacturing, automotive, energy, and instrumentation customers. This mix gives Coherent broad exposure to AI infrastructure, but also leaves results sensitive to customer spending, product transitions, and manufacturing costs.
Coherent's Fiscal Q4 FY2026 showed that the AI optics shift is accelerating. Revenue reached $2.046 billion, up 33.8% year over year, as Datacenter and Communications revenue jumped 58.6% to $1.615 billion, while Industrial revenue declined 15.8% to $430.5 million. For investors, the key question is whether 800G and 1.6T demand, higher capacity, and the NVIDIA relationship can keep driving growth fast enough to offset weaker industrial demand and support further margin expansion.
The COHR stock forecast for 2026 now centers on two competing views:
- The AI optics growth case: Strong 800G and 1.6T demand, the NVIDIA agreement, and higher manufacturing capacity could sustain rapid revenue growth and earnings upgrades.
- The execution and valuation case: Heavy capacity spending, customer concentration, and weaker industrial demand could keep cash generation from matching the stock’s 63.56% YTD gain.
This guide breaks down the COHR stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Coherent’s August 12 fiscal Q4 FY2026 earnings release, annual filing and market data through September 8, plus how to trade COHR stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Coherent Investors to Know in September 2026
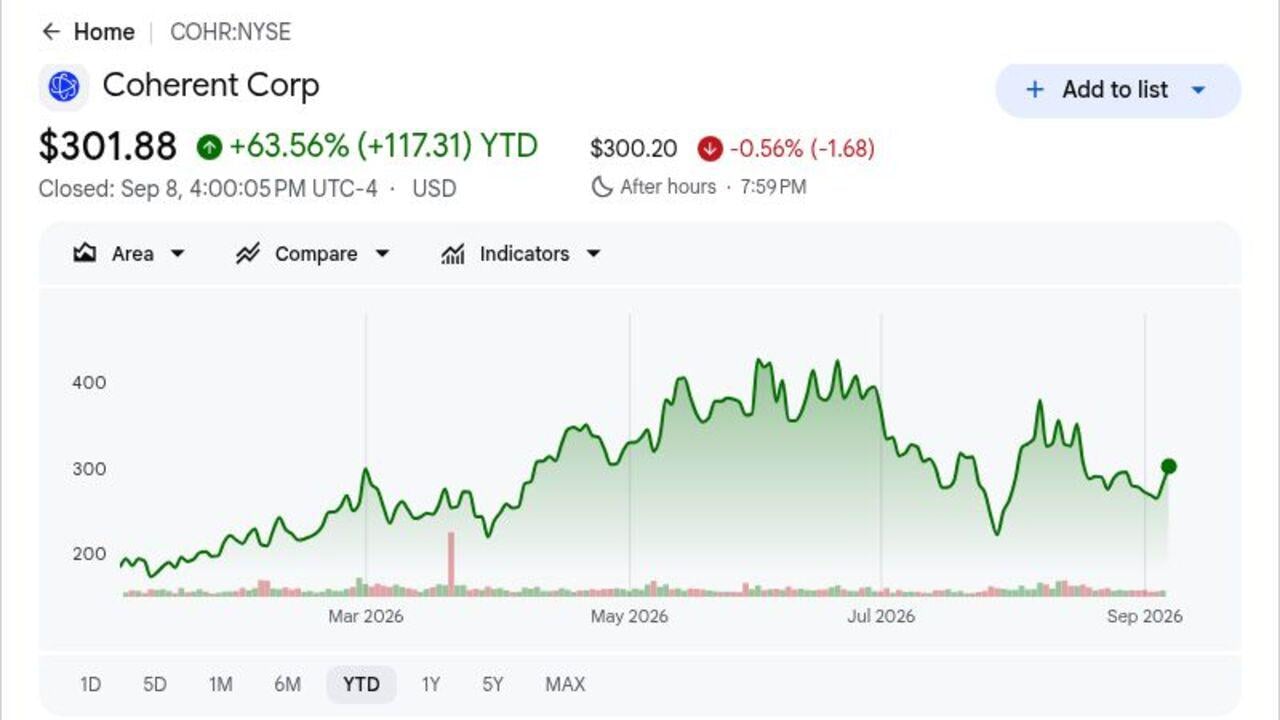
- COHR closed at $301.88 after gaining 63.56% YTD: The September 8 close followed a 7.10% daily advance and remained below the $440 high. The gap to Rosenblatt's $500 target still requires sustained earnings growth, margin expansion and AI-optics delivery.
- Q4 revenue reached $2.046 billion and grew 33.8%: Sales beat the $1.98 billion consensus by $66 million, while non-GAAP EPS of $1.74 exceeded the $1.62 estimate. The results show optical demand reaching both revenue and earnings.
- Datacenter and Communications revenue rose 58.6% to $1.615 billion: The segment generated 79% of sales and grew 18.6% sequentially. Industrial revenue fell 15.8% to $430.5 million, increasing Coherent's dependence on AI and communications infrastructure for growth and margins.
- Q1 FY2027 revenue guidance reached $2.2 billion to $2.4 billion: The $2.3 billion midpoint exceeded consensus by $160 million. The $1.95 midpoint of non-GAAP EPS guidance also topped the $1.77 estimate by $0.18, strengthening the near-term earnings setup.
- NVIDIA committed $2 billion to a multiyear optics partnership: The agreement includes a multibillion-dollar purchase commitment and capacity rights across several product families. Coherent's 20-year NVIDIA relationship provides demand visibility while increasing customer-concentration exposure, margin sensitivity and execution risk over time.
What Is Coherent (COHR)?
Coherent is a vertically integrated photonics company that designs and manufactures optical components, modules, equipment, and engineered materials. Its Datacenter and Communications business supplies transceivers, lasers, amplifiers, optical switches, and silicon-photonics products for cloud and telecom networks, while Industrial serves semiconductor equipment, manufacturing, displays, automotive, energy, and instrumentation markets. Coherent operates a global research, production, sales, and distribution network across more than 20 countries.
Its long-term strategy increasingly centers on AI networking and optical connectivity. Coherent’s 20-year relationship with NVIDIA expanded in March 2026 through a multiyear agreement covering optical products, capacity, research, and U.S. manufacturing, alongside a $2 billion NVIDIA investment and a multibillion-dollar purchase commitment. Coherent is also expanding U.S. production in Sherman, Texas, while developing 1.6T transceivers, silicon photonics, optical circuit switching, and co-packaged optics for next-generation AI data centers.
Read More: Top AI Optical Stocks to Buy in 2026: Photonics, Optics, Fiber, and Data Center Interconnects
Coherent (COHR) Q4 FY2026 Earnings Overview: Record Revenue, EPS and AI Optics Growth
Coherent reported Q4 FY2026 revenue of $2.046 billion versus the $1.98 billion consensus, non-GAAP EPS of $1.74 versus $1.62 expected and GAAP EPS of $1.19 versus a $0.83 loss a year earlier. Datacenter and Communications revenue increased 58.6% to $1.615 billion, and non-GAAP gross margin expanded 215 basis points to 40.2%. Management guided Q1 FY2027 revenue to $2.2 billion to $2.4 billion, though weaker Industrial revenue and heavy capacity spending remain the main tradeoffs.
Read More: Coherent (COHR) Q4 FY2026 Earnings News: $2.05B Revenue and AI Outlook Trigger a 7.99% Price Selloff
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q4 FY2026 revenue |
$1.98B consensus |
$2.046B |
Beat. $66M above consensus; up 33.8% YoY. |
|
Q4 non-GAAP diluted EPS |
$1.62 consensus |
$1.74 |
Beat. $0.12 above consensus; previously $1.00. |
|
Q4 GAAP net income |
— |
$240.5M |
Improved. Reversed a $95.6M loss. |
|
Datacenter & Communications revenue |
— |
$1.615B |
Accelerated. Up 58.6% YoY. |
|
Q4 non-GAAP gross margin |
— |
40.20% |
Expanded. Up 215 bps YoY. |
|
Q1 FY2027 revenue outlook |
$2.14B consensus |
$2.2B–$2.4B |
Above. Midpoint exceeded consensus by $160M. |
- Revenue of $2.046 billion beat consensus by $66 million: The 33.8% annual increase also represented 13.3% sequential growth from $1.806 billion. Both comparisons show that the optical ramp accelerated through fiscal year-end and entered fiscal 2027 with momentum.
- Non-GAAP EPS of $1.74 exceeded the $1.62 estimate: Earnings rose from $1.00, while GAAP EPS improved by $2.02 to $1.19. Volume, mix and cost execution allowed profit growth to outpace revenue and strengthened earnings quality.
- Datacenter and Communications sales rose 58.6% to $1.615 billion: The segment added $597 million and represented 79% of revenue. That concentration strengthens AI exposure while increasing dependence on hyperscaler schedules and large customers for revenue visibility and operating leverage.
- GAAP gross margin expanded 277 basis points to 38.5%: Non-GAAP margin rose 215 basis points to 40.2%. Further improvement depends on mix, pricing, cost actions and six-inch indium-phosphide manufacturing output, yields, factory utilization, product mix and pricing discipline.
- The $2.3 billion guidance midpoint topped consensus by $160 million: The $1.95 EPS midpoint was also $0.18 above estimates. Delivery would confirm demand strength, though projected operating expenses of $400 million to $420 million keep investment high.
Coherent (COHR) 2026 Investment Outlook: $500 Bull Case vs. $220 Bear Case
The test is whether Coherent can convert 800G, 1.6T, silicon-photonics and optical-switch demand into earnings and cash flow after a 63.56% YTD gain. NVIDIA improves visibility, though spending, concentration and Industrial weakness raise the execution bar.
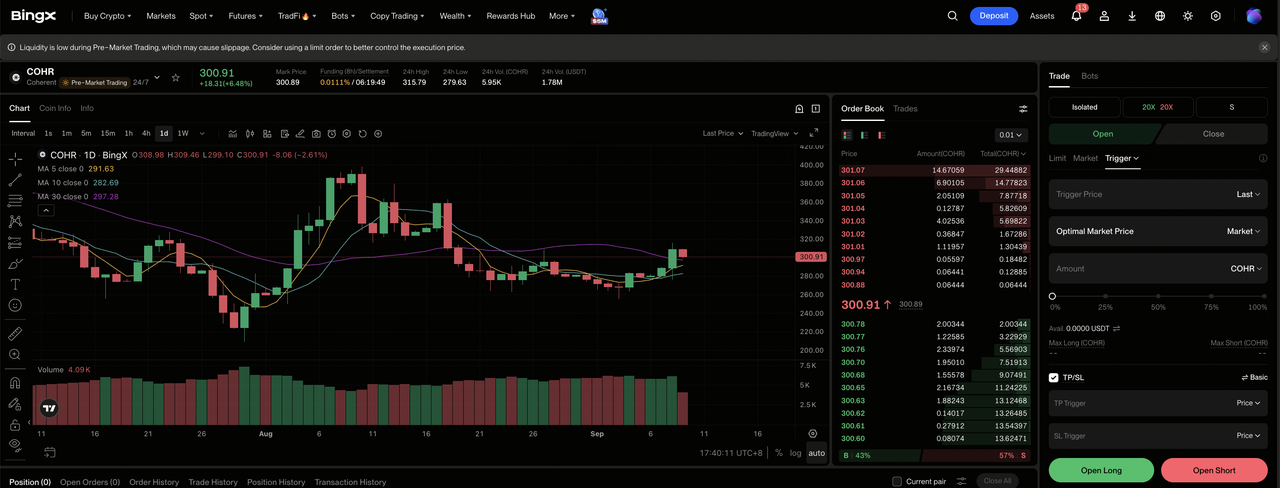
The Bull Case: Strong AI Optics Demand Pushes COHR Toward $500
The Bull Case assumes 800G and 1.6T shipments keep expanding as AI clusters require more optical links. NVIDIA’s $2 billion investment and purchase commitment improve demand visibility, while higher indium-phosphide capacity supports better utilization and margins.
A move toward $500 would require revenue near or above the $2.3 billion guidance midpoint, gross margin within the 39.5% to 41.5% range, and stronger cash conversion. Continued estimate upgrades and broader 1.6T adoption would provide the clearest confirmation.
The Base Case: Steady AI Networking Growth Keeps COHR Between $350 and $425
The Base Case assumes 800G, 1.6T, and optical-switch demand continues offsetting weaker Industrial markets. Revenue grows and margins improve, while NVIDIA commitments support volume visibility, but customer concentration and high capital spending limit further multiple expansion.
Under this scenario, COHR could trade mainly between $350 and $425. Revenue near guidance, gross margin around 40%, and on-schedule product ramps would support the range, while weaker Industrial demand or slower utilization would cap the upside.
The Bear Case: Slower AI Deployments and Margin Pressure Pull COHR Toward $220
The Bear Case assumes hyperscalers delay optical deployments while Industrial demand stays weak. Lower utilization would limit margin improvement and pressure cash flow after fiscal 2026 capital expenditure reached $1.103 billion.
A move toward $220 would become more likely if revenue falls below the $2.2 billion guidance floor, gross margin drops under 39.5%, or analyst estimates flatten. Customer concentration, technology shifts, or export restrictions could add further pressure.
COHR Stock Price Forecasts for 2026 By Wall Street Analysts
These five dated actions span $420 to $500 and are sorted high to low. It reflects different views on demand, capacity, margins and NVIDIA. The final Base and Bear rows are BingX Academy editorial scenarios rather than Wall Street forecasts or guarantees.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Rosenblatt Securities |
$500 |
Buy |
Constructive. August 19: raised from $425 on stronger 800G and 1.6T demand. |
|
Craig-Hallum |
$480 |
Buy |
Positive. August 13: raised from $400 after the earnings beat. |
|
J.P. Morgan |
$465 |
Buy |
Positive revision. August 17: raised from $435 on AI demand and guidance. |
|
Susquehanna |
$425 |
Positive |
Balanced. August 13: reiterated as AI demand offset execution risk. |
|
Stifel |
$420 |
Buy |
Constructive. August 13: raised from $412 on growth and margins. |
|
Article Base Case |
$350–$425 |
Base Case |
Balanced. Assumes datacenter growth stays strong as valuation and capacity spending limit upside. |
|
Article Bear Case |
$220 |
Bear Case |
Cautious. Assumes slower optical demand and weaker cash conversion compress earnings and valuation. |
How to Trade Coherent (COHR) Stock on BingX
Trade the COHR outlook using BingX TradFi and BingX AI tools. Because COHR reacts sharply to spending, guidance and analyst revisions, traders should define the catalyst and risk limits before entry.
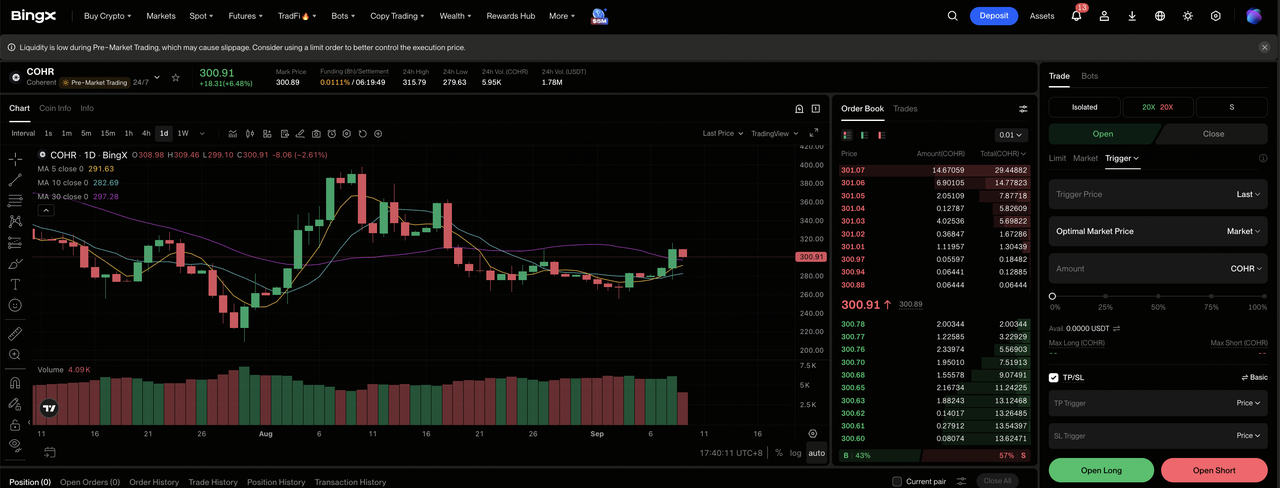
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Coherent (COHR). Search for and select the COHR-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if AI optics demand and margins support the Bull or Base Case. Select Open Short if order delays, weaker guidance or cash-flow pressure validate the Bear Case.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. COHR's 7.10% September 8 move shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. COHR can react quickly to orders, product launches, manufacturing updates and analyst revisions.
Top 5 Risks to Watch for COHR Investors in 2026
Coherent’s outlook depends on customer concentration, capacity execution, cash conversion, Industrial demand, and technology leadership.
- High expectations leave less room for disappointment: COHR was up 63.56% YTD, with selected analyst targets ranging from $420 to $500. Revenue that only meets guidance or flat margins could still trigger multiple compression.
- Large-customer exposure can amplify schedule changes: NVIDIA’s $2 billion investment and purchase commitment improve visibility, but a delayed AI platform or component change could reduce utilization, revenue, and earnings at the same time.
- Heavy capacity spending can pressure cash flow: Fiscal 2026 capex reached $1.103 billion, while operating cash flow was $79.5 million. A slower ramp could leave depreciation, inventory, and fixed costs weighing on free cash flow.
- Industrial weakness reduces diversification: Industrial revenue fell 15.8% to $430.5 million in Q4. Continued weakness in semiconductor equipment and manufacturing would make Coherent more dependent on datacenter growth.
- Technology shifts and export rules can affect orders: Coherent must execute across 1.6T transceivers, silicon photonics, optical switching, and co-packaged optics. Delays, weaker yields, rival designs, or tighter export restrictions could shift demand to competitors.
Final Thoughts: Should You Invest in COHR in 2026?
Coherent enters late 2026 with strong evidence behind the AI optics thesis. Revenue grew 33.8%, Datacenter and Communications advanced 58.6%, non-GAAP gross margin reached 40.2% and next-quarter guidance exceeded consensus. NVIDIA adds long-term visibility, though the stock's 63.56% YTD gain leaves upside dependent on estimate increases.
The Bull Case requires higher shipments, margins and cash conversion, supporting $500. The Bear Case requires delays, sub-guidance revenue or weak utilization that pulls valuation toward $220. Conservative traders may wait for another delivery near the $2.3 billion revenue midpoint before treating the current analyst range as durable evidence.
Risk Reminder: Stock futures involve leverage and liquidation risk. Price targets and scenarios are not guarantees, so traders should size positions according to their circumstances and risk tolerance.
Related Reading
- Top AI Networking Stocks 2026: AI Fabric, Switches, Copper, Fiber, and Optics Connectivity
- Top AI Optical Stocks to Buy in 2026: Photonics, Optics, Fiber, and Data Center Interconnects
- NVIDIA (NVDA) Price Prediction 2026: Can AI Infrastructure Growth Drive NVDA Toward $420?
- AAOI Price Prediction 2026: Can the 1.6T Ramp Push AAOI Toward $250?
- Lumentum Stock Forecast 2026: Can AI Optics Boom, AI Data Center Supercycle Drive LITE Above $1,200?
- AXT Inc. (AXTI) Price Prediction 2026: Can AI Optical Demand Push AXTI Toward $125?
